
This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.
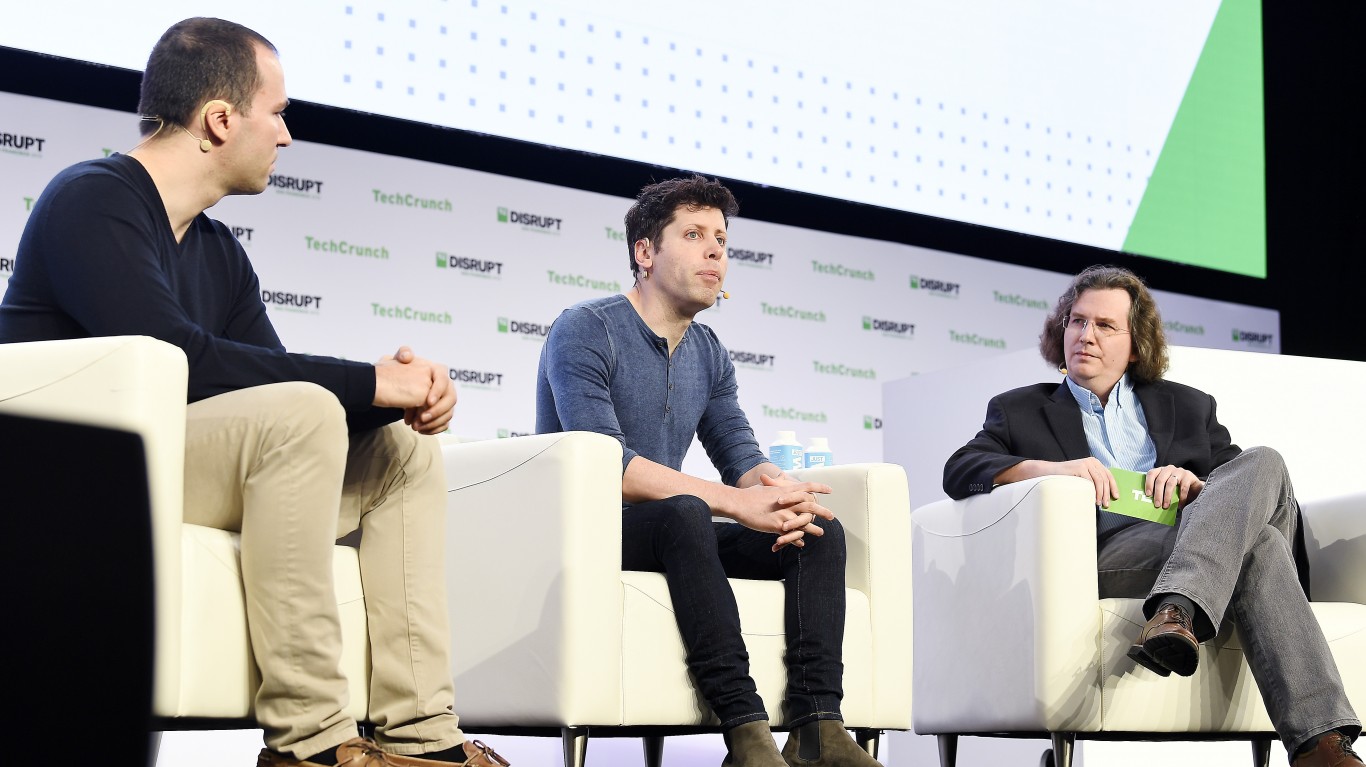
At Semafor’s November 16 Silicon Valley & the World event, OpenAI’s chief executive, Sam Altman, pointed to a weak spot in the AI hardware boom. Many suppliers are planning around the same few buyers. He made the remarks as AI stocks fell. NVIDIA (NASDAQ:NVDA | NVDA Price Prediction) is down 28.88% over the past month.
“There are now many people making chips. And many of those people think they’re going to sell most of the volume to us and Anthropic, and others. And we have some limited amount of demand and data centers, and everything else. And I think there are many people making chips, all talking to the silicon supply chain, assuming that we’re going to buy all of their chips,” Altman said.
24/7 on YouTube 6:47Play: OpenAI vs Google In 2026
OpenAI vs Google In 2026
Altman said underlying data center demand remains solid and that long-term computing demand should keep growing. His concern is timing. He questioned whether supply and demand will match over shorter periods when several suppliers may be banking the same future orders. (The expansion still has to be powered, cooled, and connected by somebody, and we pulled together seven of those non-chip suppliers in a free AI infrastructure report.)
Every Supplier Is Selling to the Same Labs
In August, NVIDIA’s chief executive at the time, Jensen Huang, said “OpenAI has committed to substantial deployments of NVIDIA AI infrastructure through 2030,”[1] which amounts to about 12 gigawatts. NVIDIA expects AI labs backed by its balance sheet to make up “roughly a quarter of our business next year[1].” It posted Q2 revenue of $96.22B[2] and guided Q3 to $108B +/- 2%.
Advanced Micro Devices (NASDAQ:AMD) has its first Helios racks running workloads for Anthropic, Meta, Microsoft, OpenAI and Oracle Cloud Infrastructure. CEO Lisa Su said “It is true that demand is higher than supply,”[3] and AMD expects 2027 revenue growth above 80%.
Micron Technology (NASDAQ:MU) has “more than 75% of our shipments committed” for fiscal 2027. Management also said it lacks “line of sight to when supply and demand balance.” Its fiscal Q4 revenue rose 379.3%.
At Coherent (NYSE:COHR), CEO Jim Anderson said “Calendar 27 is basically booked out and the customers are booking out calendar 28 now.” The company also signed a PhotonLink agreement worth about $20 billion with a major AI company.
Neoclouds Carry the Financing Risk
CoreWeave (NASDAQ:CRWV) plans fiscal 2026 capex of $37B-$39B[4]. In Q3 it posted $846M[4] in net interest expense and a $709M net loss. CEO Michael Intrator said “We are not a growth-at-all-costs business.” The stock is down 33.12% year to date.
IREN co-CEO Daniel Roberts said investor questions “have undoubtedly moved from how big the contract is to whether it can be delivered, financed, and run at a profit.” Net debt rose to $4.43B from $216M, and the shares fell 42.39% in a month.
What to Watch Next
NVIDIA’s next earnings report is its first since Huang’s ouster. Watch whether it names the same leading research labs that AMD, Micron, and Coherent cite. Demand concentration is now a stated risk at the buyer level too. Anthropic’s October 26 S-1 says it “may be committed to excess compute that remains underutilized.”
Contact [email protected] for any questions or corrections.